When a home appraisal comes back lower than expected, it can put an otherwise solid deal at risk. But a low appraisal does not automatically mean the home is overpriced.
In my experience, low appraisals usually come down to one of three issues: inaccurate information or poor comparable sales, a market that has not caught up with current construction costs, or valuable home features that were never properly documented for the appraiser.
What Should You Do First If an Appraisal Comes Back Low?
Before anyone starts renegotiating the deal, the first step is figuring out why the appraisal came back low.
That matters because the right response depends on the cause.
I usually look at three possibilities:
- The appraiser used incorrect property information or weak comparable sales.
- The appraisal reflects the current market, but recent comps have not caught up with actual construction costs.
- The home includes added value, such as green building features or certifications, that was not fully documented.
Once you know which issue you are dealing with, you can decide whether the best next step is correcting the appraisal, reconsidering the financing, or providing additional documentation.
What If the Appraiser Used Incorrect Information?
Start by auditing the basic property information.
Errors in an appraisal can have a larger effect than homeowners expect, especially with custom homes where the property may not fit neatly into a standard comparison.
Check details such as:
- Bedroom and bathroom count
- Heated square footage
- Covered and unheated square footage
- Lot size
- Location adjustments
- Mechanical systems
- Outdoor living areas
- Other measurable property features
Even small mistakes can change how the home is compared with other properties.
I would also look closely at the distinction between conditioned living space and other areas of the home. Custom homes often have porches, garages, lower levels, utility areas, and outdoor spaces that may be treated differently within an appraisal.
How Do You Know If the Comparable Sales Are Wrong?
The next thing I look at is the quality of the comparable sales, or comps.
A nearby home is not automatically a good comp.
For a custom or high-end home, the comparison should consider more than location and square footage. Construction quality, finish level, acreage, view, energy performance, and the overall market segment can all matter.
Ask questions such as:
- Is the construction quality comparable?
- Are the finishes similar?
- Is the acreage reasonably similar?
- Does the view or setting compare?
- Are the homes targeting the same buyer?
- Are the comps truly custom homes?
- Do they have similar certifications or performance features?
If the comparable properties are clearly a tier below the subject home, the resulting value may not tell the full story.
This is one area where custom homes can be difficult to appraise. The more distinctive the property becomes, the harder it can be to find a recent sale that genuinely matches it.
Can You Challenge a Low Appraisal?
Yes. If you find factual errors, missing information, or questionable comparable sales, you may be able to request a reconsideration of value through the lender.
The goal is not simply to say that the appraisal feels too low. You need to show why the valuation may need another look.
A strong reconsideration may include:
- Corrected property information
- More appropriate comparable sales
- Construction-cost documentation
- Certification records
- Energy-performance information
- Prior appraisal information, where relevant
- Documentation of features that were not addressed
The clearer and more objective the information is, the more useful it becomes.
If the issue appears to be that the appraiser is unfamiliar with the local market or the level of construction involved, the buyer and lender may also discuss whether another appraisal is appropriate.
What If the Market Has Not Caught Up With the Home’s Cost?
This is a different problem.
Sometimes the appraisal is not necessarily based on incorrect information. The challenge is that comparable sales do not yet reflect what it currently costs to design and build a similar home.
We have seen this happen with custom construction.
A project may be appropriately designed and priced based on current labor, materials, land, and construction standards, while the recent sales available to the appraiser still reflect an earlier market.
Months later, new sales can begin appearing at higher values and support the cost basis that already existed.
That does not make the appraisal meaningless. It simply means there can be a gap between today’s construction costs and yesterday’s comparable sales.
What Options Are Available When There Is an Appraisal Gap?
When the appraisal itself is reasonable but the value still comes in below the contract price, the conversation usually shifts from challenging the report to keeping the transaction workable.
Depending on the buyer, seller, lender, and contract, possible options may include:
- Extending the closing date or contingency period
- Bringing additional cash to closing
- Renegotiating the purchase price
- Negotiating a seller credit
- Exploring temporary gap or bridge financing
- Planning for another appraisal later, if appropriate
The right approach depends heavily on the financing structure and the terms of the transaction.
The important thing is not to assume that a low appraisal automatically ends the deal.
There may be several ways to address the gap once everyone understands why it exists.
Can Energy-Efficient Features Affect an Appraisal?
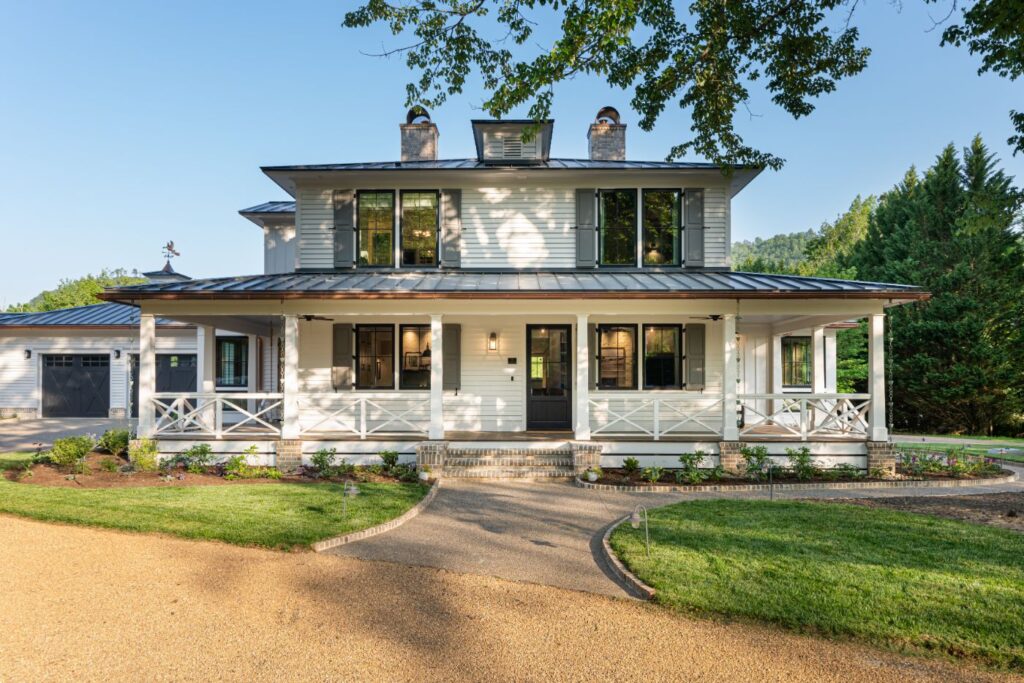
They can, but those features need to be clearly documented.
A custom home may include meaningful investments in energy efficiency, green building, indoor air quality, high-performance construction, or aging-in-place design.
The problem is that an appraiser cannot necessarily assign value to something that is never clearly presented.
That is why documentation matters.
If a home has third-party certifications, energy ratings, upgraded building systems, or other measurable performance features, that information should be organized and available as early as possible.
Waiting until after a low appraisal comes back makes the process more difficult.
Why Should Green Building Documentation Be Prepared Early?
The best time to organize this information is before the appraisal takes place.
If the property has certified or independently documented features, the appraiser should have access to clear information about what those features are and how they differ from a standard home.
That may include documentation related to:
- Energy efficiency
- Green building certifications
- Indoor air quality
- High-performance HVAC systems
- Insulation and building-envelope performance
- Water-efficiency features
- Aging-in-place or universal design features
The goal is not to tell the appraiser what the home should be worth.
The goal is to make sure meaningful property characteristics are not overlooked simply because they are difficult to see during a standard walkthrough.
What Should a Reconsideration of Value Include?
When we have helped organize information for a reconsideration of value on a custom or certified home, several categories tend to deserve a closer look.
Are the site and land characteristics accurate?
Lot size, acreage, ownership, privacy, topography, and other site characteristics can materially affect how a property compares with nearby sales.
If those details are incomplete or incorrect, they should be documented.
Were the home’s certifications considered?
Energy-efficiency certifications, green building credentials, indoor air quality features, and other third-party documentation may help explain why a home differs from the available comps.
If those items are absent from the appraisal, they are worth identifying.
Are the property details correct?
Review the appraisal for factual issues involving items such as:
- Heating and cooling systems
- Appliances
- Living area
- Conditioned floor area
- Outdoor living space
- Site improvements
- Structural features
Sometimes the strongest reconsideration starts with correcting straightforward factual errors.
Does the reported living area match other documentation?
Custom and high-performance homes may have several different measurements in circulation.
An appraisal’s gross living area may differ from conditioned floor area documented by an energy rater or another third party.
That does not automatically mean one measurement is wrong, but a major discrepancy should be understood and explained.
Does the appraisal reflect the quality of construction?
A newly completed custom home may have a construction cost that looks high compared with older nearby sales.
That alone does not prove the home is worth the full construction cost, but it can provide important context when the property has no obvious functional or economic obsolescence and the comps differ substantially in quality.
Does the property have features that are difficult to replicate?
Some homes include features that are genuinely unusual.
That could be a significant view, substantial acreage, unique site characteristics, or another feature that is difficult to find in a comparable property.
The appraisal should still rely on market evidence, but those differences deserve to be identified rather than ignored.
Why Is It Better to Address Appraisal Risk Early?
The earlier appraisal risk is identified, the more options everyone has.
Once a low appraisal arrives just before closing, buyers, sellers, lenders, agents, and builders are all working under pressure.
It is much easier to prepare the relevant information beforehand.
For a custom or certified home, that may mean assembling:
- Final construction information
- Energy documentation
- Certifications
- Accurate square-footage records
- Site details
- Relevant property features
- Supporting market information
Good documentation does not guarantee a particular appraised value.
What it does is give the appraiser a more complete picture of the property before forming an opinion of value.
What Should You Do If Your Appraisal Comes Back Too Low?
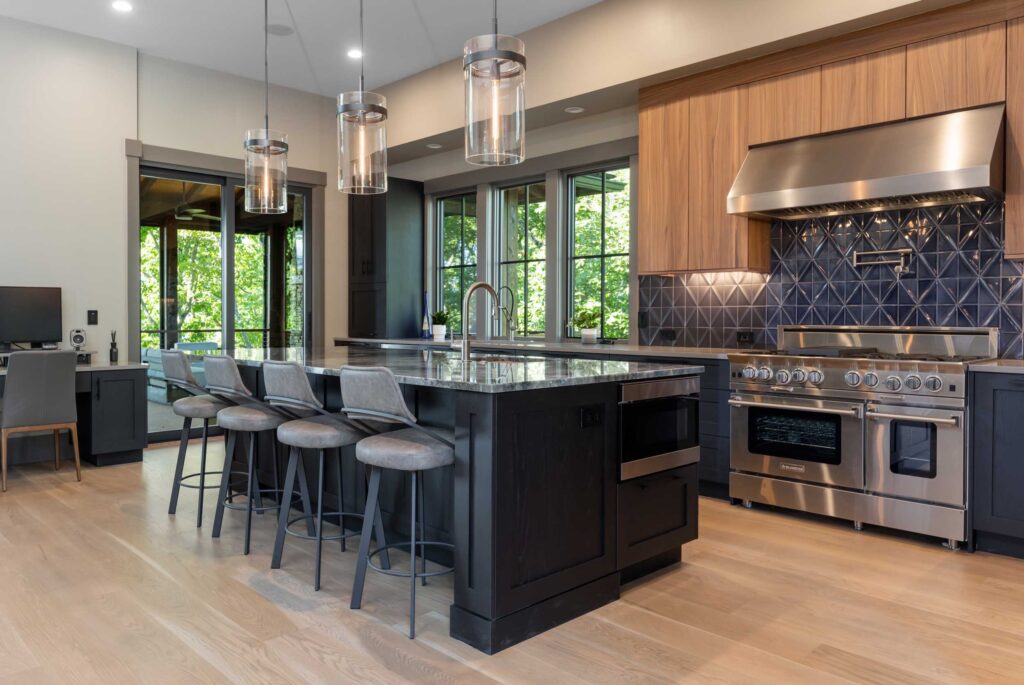
Do not start by assuming the deal is dead.
Start by asking why the appraisal is low.
Check the facts. Review the comparable sales. Make sure important construction details and certifications were documented. Then decide whether the situation calls for a reconsideration of value, a financing solution, a renegotiation, or another approach.
For custom homes, especially high-performance or certified homes, the details matter.
At Living Stone Design + Build, we can help clients organize construction-cost documentation, certification information, and other property details that may be useful when questions arise around a custom home’s appraisal.
If you are selling, buying, or building a custom home and appraisal risk is becoming a concern, it is better to address it early rather than wait until closing is at risk.
Frequently Asked Questions About Low Home Appraisals
What happens if the appraisal is lower than the purchase price?
The lender typically bases financing on the appraised value rather than automatically lending against the full purchase price. The buyer and seller may need to renegotiate, address the difference with additional funds, or explore another solution with the lender.
Can an appraisal be changed?
An appraisal may be reconsidered if there are factual errors, missing information, or relevant comparable sales that were not considered. The request usually goes through the lender.
Can I request another appraisal?
Possibly. Whether another appraisal is available depends on the lender, loan program, and circumstances surrounding the original report.
Do custom homes have more appraisal challenges?
They can. Unique architecture, higher construction quality, larger lots, unusual features, and limited comparable sales can make custom homes harder to evaluate using standard nearby sales.
Can green building features increase home value?
They may contribute to a home’s value, but the appraisal depends on market evidence and how those features are documented and recognized within the local market.
Should I give the appraiser information about the home?
Providing accurate property information, certifications, plans, energy documentation, and other relevant records can help ensure the appraiser understands features that may not be obvious during the property inspection.